Learn how McLean buyers can plan for jumbo and move-up financing, from down payments and reserves to rate sensitivity and mortgage prep that supports stronger offers.

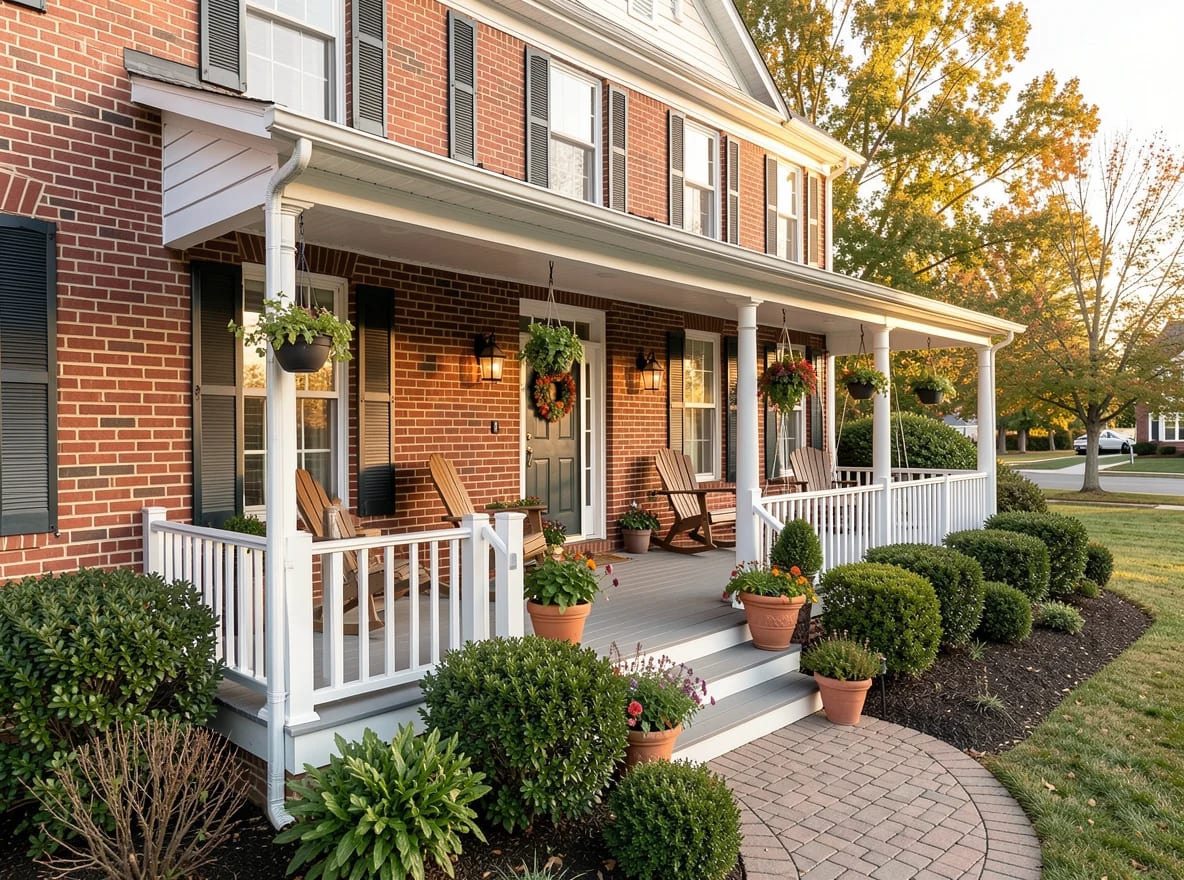
For DC-area professionals planning a move-up purchase, McLean stands out because it combines long-term lifestyle appeal with the realities of a higher-price housing market. Families are often drawn first by the area's strong school reputation, established neighborhoods, and the sense of space created by tree-lined streets, larger lots, and a polished suburban setting just outside Washington. That appeal matters when buyers are weighing whether a jumbo loan, a larger down payment, or the timing of a sale-and-purchase move makes financial sense.
McLean also offers practical convenience that supports demand: access to major commuter routes, proximity to the broader DC metro job base, and a housing mix that ranges from classic colonials to newer custom homes. For buyers stepping up from a previous home, that means financing decisions are rarely separate from neighborhood goals. In a market where price points can rise quickly, early mortgage preparation, reserve planning, and a clear budget can make the relocation process smoother from the start.
For buyers planning a jumbo or move-up purchase in McLean, neighborhood choice directly affects financing strategy. Langley often sits at the top of the price range, with large brick colonials, newer custom homes, and expansive lots that can push buyers into higher down payment and reserve requirements. Families drawn to Langley are usually paying for estate-style settings, mature tree cover, and a strong long-term reputation, so it helps to review cash reserves and monthly payment comfort before touring at the upper end of the market.
Chesterbrook can offer a different financial profile. Buyers may find traditional center-hall homes, split-levels, and updated older properties on established streets with easier access toward Washington. That mix can create more flexibility for move-up households comparing renovation costs, loan size, and rate sensitivity. Salona Village is another neighborhood where families often balance space, lot size, and convenience, with a blend of classic homes and newer construction that can change pricing block by block.
In practical terms, each neighborhood calls for a different offer strategy. Higher-priced sections of McLean may require stronger reserves, cleaner financing, and tighter budgeting for taxes, insurance, and improvements after closing. Comparing Langley, Chesterbrook, and Salona Village through both lifestyle and payment structure helps families target the right part of McLean before they compete.
For move-up buyers in McLean, school decisions often shape both home search boundaries and financing strategy. Families comparing neighborhoods near highly regarded public options such as Langley High School and McLean High School, along with well-known private campuses in the broader area, should expect competition to intensify when a property aligns with both commute needs and academic priorities. That matters in a jumbo or higher-balance purchase, where down payment reserves, monthly payment comfort, and timing all need to be mapped out before touring seriously.
In practice, buyers often narrow choices by pyramid, extracurricular fit, and community involvement, then discover that the most desirable pockets can command stronger offers and less room for financing delays. McLean's school-centered demand can influence price sensitivity from one street to the next. For households balancing tuition considerations, move-up equity, or reserve requirements, it helps to evaluate school goals and mortgage readiness together so the home search stays realistic, competitive, and aligned with long-term family plans.
For households planning a jumbo or move-up purchase, McLean's appeal is not just its housing stock—it is the daily convenience that helps justify a higher monthly payment and larger cash commitment. Family-friendly amenities are woven into the lifestyle here, from neighborhood parks and wooded trails near Scott's Run to recreation options that support youth sports, tennis, and active weekends. For buyers comparing payment scenarios, these built-in quality-of-life advantages can make a meaningful difference when deciding whether to stretch for more space in McLean rather than in a less established suburb.
That value also shows up in everyday errands and leisure. Residents benefit from village-style shopping, café patios, dining options suited to both weeknights and special occasions, and easy access to cultural destinations tied to the broader Washington area. In practical terms, that means less compromise after closing: families can prioritize convenience, activities, and community access without giving up proximity to work corridors and regional amenities. For move-up buyers, this is why financing preparation matters. A stronger down payment plan, realistic reserve strategy, and careful review of payment sensitivity can position buyers to compete for a home in a location where the lifestyle supports long-term satisfaction as much as the property itself.
For families relocating to McLean, the smartest first step is building a financing plan before touring homes. In a market where move-up and jumbo purchases are common, buyers should review cash available for down payment, closing costs, reserves, and any overlap between selling one home and buying the next. That preparation matters in neighborhoods with larger brick colonials, custom homes, and tree-lined streets where pricing can move quickly.
It also helps to map out practical relocation steps early: compare commute patterns, confirm school enrollment timelines, and identify nearby resources such as parks, shopping, and everyday services that will shape your routine after the move. Because Paul Chung has experience in both real estate and mortgage lending, he can help families think through affordability, timing, and offer strategy together. For buyers moving into McLean from elsewhere in the DMV, that kind of planning can reduce surprises and make the transition feel more manageable.
Sign in with your email address
You’re being redirected to the page with listing data.